Contributed by: Henry, FreeTaxUSA Agent, Tax Pro

Health Savings Accounts (HSAs) are a great way to pay for qualified medical expenses while receiving tax advantages. If you have a high-deductible health plan (HDHP), you may be eligible to contribute to an HSA.
However, the IRS sets annual HSA contribution limits, and exceeding those limits may result in tax penalties. This article explains the rules that apply when you and your spouse both have HSAs, including how you may allocate contributions between your HSAs while staying within the applicable limit.
For more information about the advantages of contributing to an HSA, who is eligible to contribute, the tax implications, and excess contributions, see the Community article “How do Health Savings Accounts and excess contributions impact taxes?”
What if you and your spouse both have self-only HDHP coverage?
In this situation, you may each contribute up to the annual self-only HSA contribution limit to your own HSA. If you are age 55 or older by the end of the tax year, you may make an additional $1,000 catch-up contribution to your own HSA. The same rule applies to your spouse.
Employer contributions, if any, count toward the applicable contribution limit for the spouse whose HSA receives the contribution. The IRS may adjust HSA contribution limits annually for inflation, so check the current version of Publication 969 for the relevant tax year limits. For 2026, the self-only contribution limit is $4,400.
Example 1: In 2026, Grant and Mary each have separate self-only HDHP plans, and Grant is age 55 or older. Grant may contribute up to $5,400 to his HSA – the $4,400 self-only contribution limit plus a $1,000 catch-up contribution. Mary may contribute up to $4,400 to her HSA. Their combined contributions may total up to $9,800.
What if at least one spouse has family HDHP coverage?
Now let’s look at situations where 1) you and your spouse each have separate family HDHP coverage, or 2) one spouse has family HDHP coverage and the other has self-only HDHP coverage.
If either you or your spouse has family HDHP coverage, both of you are treated as having family coverage. This is true even if you have separate plans and separate HSAs. The family contribution limit applies to both spouses collectively – not to each of you separately. You may generally allocate the family limit between your HSAs in any manner you choose, but your combined regular contributions can’t exceed the applicable limit.
For 2026, the family contribution limit is $8,750. If you or your spouse is age 55 or older by the end of the tax year, that spouse may make an additional $1,000 catch-up contribution to that spouse’s own HSA. If both of you qualify, your combined limit may total up to $10,750.
Example 2: In 2026, Fisher and Madeleine are married, and both are under age 55. Fisher has self-only HDHP coverage, while Madeleine has family HDHP coverage. Because Madeleine has family coverage, the family contribution limit applies to their combined contributions. Their combined limit is therefore $8,750 for the year.
Fisher contributes $6,000 to his HSA, and Madeleine contributes $2,750 to hers. Their total contributions equal $8,750, so they don’t exceed the applicable family limit. Even though Fisher has self-only HDHP coverage, he may contribute more than the self-only limit because their combined contributions are subject to the family limit.

Does the contribution limit have to be split equally between spouses if you both have an HDHP plan?
No. You and your spouse don’t have to split the contribution limit equally, so proper allocation is important.
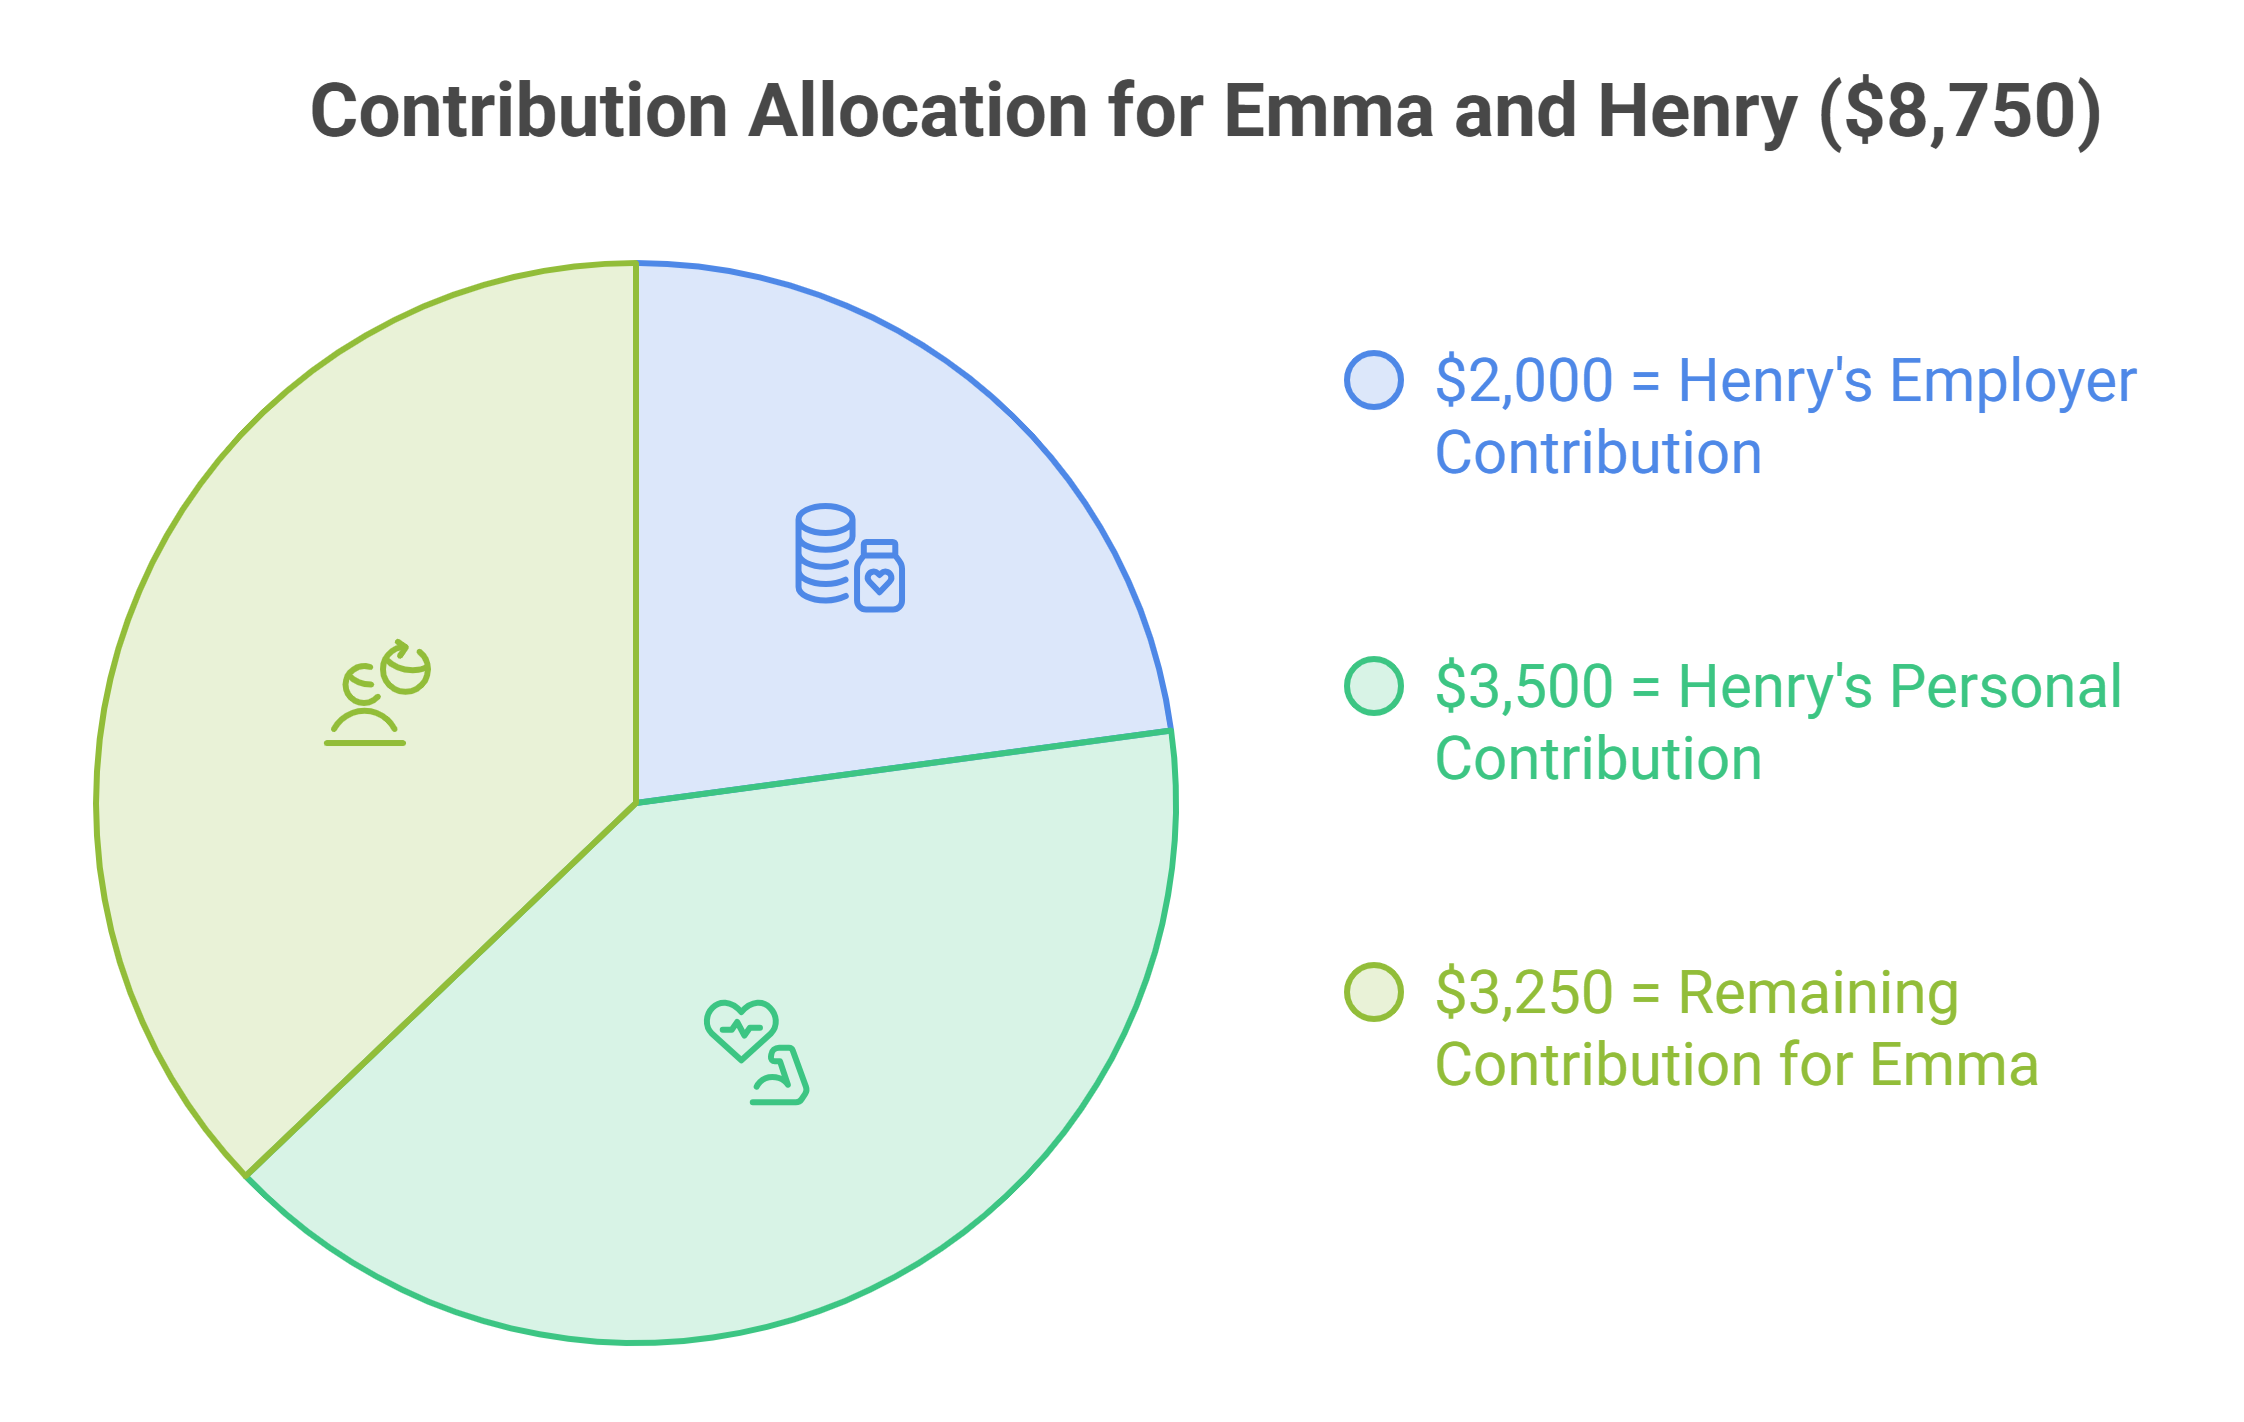
Example 3: In 2026, Emma and Henry each have separate family HDHP plans, and both are under age 55. Henry’s employer contributes $2,000 to his HSA, and Henry contributes an additional $3,500, bringing his total contributions to $5,500.
Because either spouse’s family HDHP coverage makes the family contribution limit apply to both spouses, Emma and Henry have a combined limit of $8,750 for the year. After accounting for Henry’s $5,500 in contributions, $3,250 remains available for Emma to contribute to her HSA without exceeding their combined annual limit.
$8,750 − $2,000 − $3,500 = $3,250
Remember, each $1,000 catch-up contribution is available only to the eligible spouse. It must be made to that spouse’s own HSA and can’t be allocated or transferred to the other spouse’s HSA.
Example 4: In 2026, Quincey and James each have separate family HDHP plans, and both are age 55 or older. Together, they want to contribute the maximum allowable amount of $10,750 to their HSAs.
Quincey doesn’t usually contribute much to her HSA. However, because each $1,000 catch-up contribution must be made to the HSA of the spouse who qualifies for it, Quincey must put at least $1,000 in her own HSA if they want to contribute the maximum amount. They can then allocate the remaining $8,750 of the standard family contribution limit to James, who can also make his own $1,000 catch-up contribution to his HSA.
As a result, Quincey contributes $1,000 and James contributes $9,750, for a combined total of $10,750.

Allocating HSA Contributions in FreeTaxUSA
1. HSA contribution allocations are entered on the final page of the Health Savings Account (HSA) (1099-SA) section. Follow the menu path: Deductions/Credits > Other Deductions/Credits > Health Savings Account (HSA) (1099-SA).
2. Enter each spouse’s information, including coverage details, distributions received, and contributions made. You’ll then reach a screen titled How should we split the HSA contribution limit?

3. The software automatically selects Yes in response to the question, “Would you like to divide the contribution limit equally between [taxpayer] and [spouse]?” Select No to enter a custom allocation.
4. Enter the applicable contribution amount for each spouse.

💡 Note: If either spouse is age 55 or older, don’t include the $1,000 catch-up contribution in your manual allocation (as shown above). The software automatically assigns it to the eligible spouse.
5. Make sure the amounts allocated between the spouses total the standard family contribution limit for the year.
6. Click Save and Continue.
Key Points to Remember
- Spouses who each have separate self-only HDHP coverage have separate annual HSA contribution limits.
- Spouses with family HDHP coverage share one combined annual HSA contribution limit.
- Contributions don’t have to be divided equally between spouses.
- Employer contributions count toward the combined contribution limit.
- Each spouse age 55 or older must make their own $1,000 catch-up contribution.
- Catch-up contributions aren’t included in the manual allocation.
- Use the custom allocation option in FreeTaxUSA to assign contributions between spouses.
- Track all contributions carefully to avoid exceeding the limit and incurring potential tax penalties.
Help is available
HSA contributions can be complicated. If you have a tricky situation or need help entering your information, FreeTaxUSA Customer Support is available.